Moving to US on permanent residency? Financial implications Indian parents should weigh
Indian parents getting US permanent residency must review bank, mutual fund and share holdings; FEMA treats holding resident accounts as illegal. MF Analyser outlines the compliance shift.
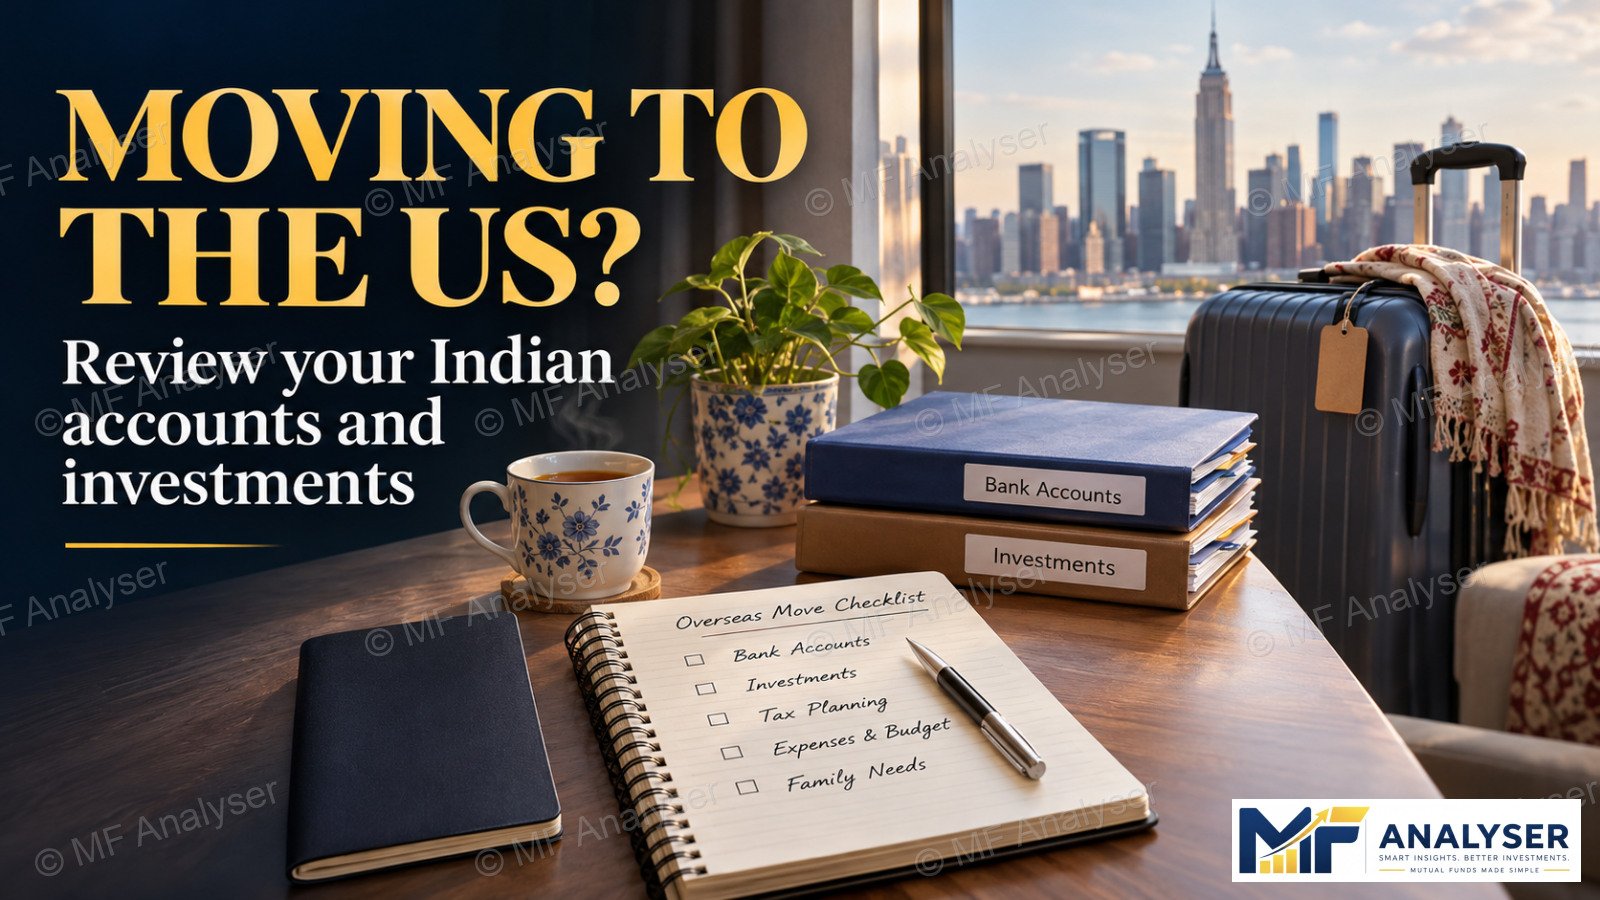
This is a compliance-driven reset for existing accounts and investments, not a market event, but it carries real penalties if ignored.
- FEMA makes it illegal to hold resident bank and demat accounts after moving abroad on permanent resident status.
- Investments in bank accounts, mutual funds, shares and other assets must be reviewed and modified.
- FATCA forms disclosing residency are part of the compliance process.
Economic Times reports that Indian parents getting US permanent residency must review and modify investments across bank accounts, mutual funds, shares and other assets. The reason is compliance: India’s FEMA rules change what is allowed once a person becomes a non-resident.
What happened
According to Economic Times, it is illegal under FEMA to hold resident bank and demat accounts after moving abroad on permanent resident status. Such accounts must be converted to non-resident, and FATCA forms disclosing residency are part of the process.
Our analysis
This is not about investment performance; it is about legal status. Once an Indian parent becomes a US permanent resident, resident accounts and holdings sit on the wrong side of exchange-control rules. The shift forces a review of every financial asset, because the designations and disclosures attached to those accounts must match the new residency.
In our view, the burden falls mainly on those who hold assets across multiple institutions. A single missed account conversion or FATCA disclosure can create regulatory friction later, even if the investments themselves remain unchanged.
What this could mean for you
- NRIs and US-bound Indian parents may need to convert resident bank and demat accounts and update residency-related disclosures.
- Mutual fund and stock investors holding Indian assets would likely face a review of each holding and account type.
- Families with multiple bank accounts may face extra coordination, since every resident account must be reclassified.
What to watch next
- Clarity on the practical steps for converting accounts and completing FATCA disclosures.
- Any updated guidance from banks and depositories on timelines for non-resident reclassification.
Bottom line
The rule is a status change, not a market signal. The key is recognising that resident account structures and FATCA disclosures may need to be updated before or soon after the move.
Source: Economic Times — Indian parents getting US residency? 6 financial implications to consider before applying. This story was written by the MF Analyser News Desk with AI assistance and its figures were checked automatically against the original report. It is for education only and is not investment advice. Mutual fund investments are subject to market risks.